


In August 2026 risk of mortgage stress virtually unchanged at 32.3%, but up a large 8.4% points since January
New research from Roy Morgan shows 32.3% of mortgage holders ‘At Risk’ of ‘mortgage stress’ in the three months to August 2026, down 0.2% points from July 2026, but up a large 8.4% points since January after three interest rate increases from the Reserve Bank (RBA) early this year.
After raising interest rates in February (+0.25%), March (+0.25%) and May (+0.25%) to 4.35%, the RBA subsequently elected to leave interest rates unchanged at their recent meetings in June and August. Today’s interest rates increase of +0.25% to a 15-year high of 4.6% will impact future mortgage stress.
A share of 32.3% of mortgage holders ‘At Risk’ of mortgage stress is equivalent to 1,718,000 people – down 68,000 on a month earlier, but up a large 534,000 so far this year.
The record high of 35.6% of mortgage holders ‘At Risk’ of mortgage stress was reached in mid-2008 when official interest rates hit a 30 year high of 7.25% (March – September 2008).
The number of Australians ‘At Risk’ of mortgage stress is up 295,000 on a year ago
The number of Australians ‘At Risk’ of mortgage stress is up 295,000 on a year ago after the RBA of Australia cut interest rates in August 2025 (-0.25%) but then raised them back up in February 2026 (+0.25%), March 2026 (+0.25%) and again in May 2026 (+0.25%). As a result of these changes, interest rates were at 4.35% in August 2026, 0.75% higher than a year earlier in August 2025
The number of Australians considered ‘Extremely At Risk’, is now numbered at 1,207,000 (22.7% of mortgage holders) which is significantly above the long-term average over the last two decades of 16.4%.
Mortgage Stress – % of Owner-Occupied Mortgage-Holders
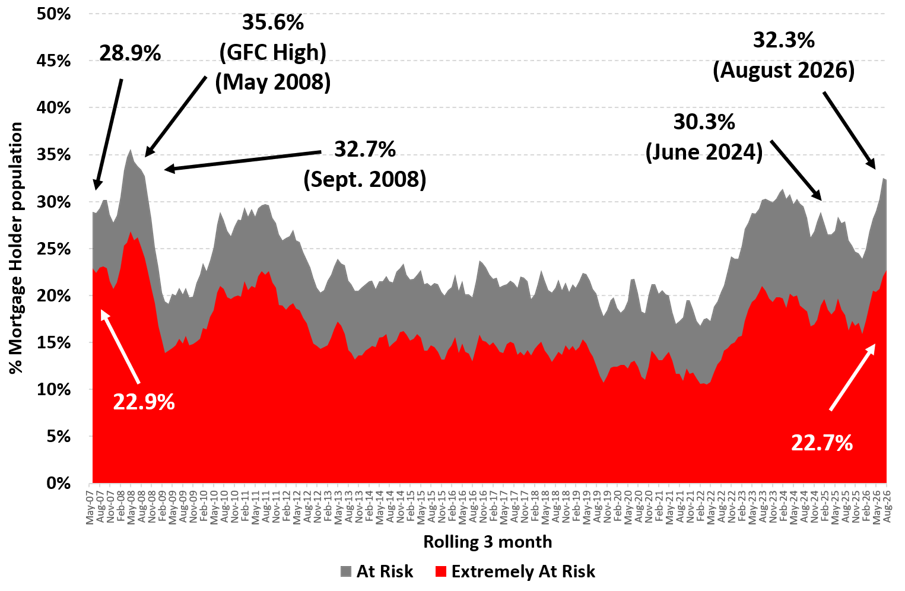
Source: Roy Morgan Single Source (Australia), average interviews per 3-month period April 2007 – August 2026, n=2,903.
Base: Australians 14+ with owner occupied home loan.
Mortgages ‘At Risk’ set to rise as the Reserve Bank increases interest rates again
The Reserve Bank (RBA) raised interest rates three times in early 2026. These increases were due to the official ABS annual inflation rate being above the RBA’s preferred target range of 2-3%. Official estimates of inflation were at 3.5% in the year to July 2026 – still above the RBA’s preferred target range.
Because of this, Roy Morgan modelled the impact of potential RBA interest rate increases at their meetings this week (+0.25% to 4.6%) and in early November (+0.25% to 4.85%).
The RBA decision to increase interest rates this week to 4.6% will likely see the share of mortgage holders considered ‘At Risk’ of mortgage stress increase to 32.5% (up 0.2% points from now), and equivalent to 1,730,000 mortgage holders, up 12,000 from now. This impact would grow in October with the share of mortgage holders considered ‘At Risk’ increasing to 32.9% (up 0.6% points from now), and equivalent to 1,750,000 mortgage holders, up 32,000 from now.
Looking forward into November, and another potential RBA interest rate increase of +0.25% to a 15-year high of 4.85%, the share of mortgage holders considered ‘At Risk’ would then increase to 33.9% (up 1.6% points from now), and equivalent to 1,801,000 mortgage holders, up 83,000 from now.
Mortgage Risk projections based on an interest rate increases in September & November 2026
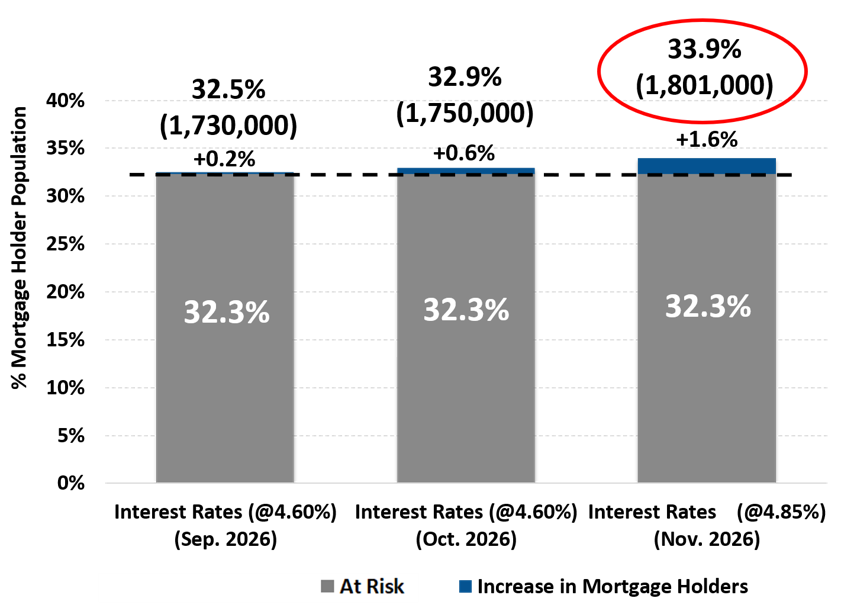
Source: Roy Morgan Single Source (Australia), June 2026 – August 2026, n=3,578.
Base: Australians 14+ with owner occupied home loan.
How are mortgage holders considered ‘At Risk’ or ‘Extremely At Risk’ determined?
Roy Morgan considers the risk of ‘mortgage stress’ among mortgage holders in two ways:
Mortgage holders are considered ‘At Risk’[1] if their mortgage repayments are greater than a certain percentage of household income – depending on income and spending.
Mortgage holders are considered ‘Extremely at Risk’[2] if even the ‘interest only’ is over a certain proportion of household income.
Unemployment is the key factor which has the largest impact on income and mortgage stress
It is worth understanding that Roy Morgan uses a conservative forecasting model, essentially assuming all other factors apart from interest rates remain the same.
The latest figures on mortgage stress show that weakness in employment markets is beginning to negatively impact levels of household income. This impact is supported by the latest Roy Morgan unemployment estimates which show over one-in-five Australian workers are either unemployed or under-employed – 3,293,000 (20.8% of the workforce) – and a drop in both the workforce and employment; (In August Australian ‘real unemployment’ was virtually unchanged at 11.7%, but workforce and employment both contracted).
Although the Reserve Bank’s decision to cut interest rates three times last year had a positive impact and helped lower mortgage stress, since the turn of the year the Reserve Bank has reversed course and has now increased interest rates on three occasions already this year in February, March, and May.
Despite the actions of the Reserve Bank, the fact remains the greatest impact on an individual, or household’s, ability to pay the mortgage is not interest rates, it’s if they lose their job or main source of income.
Michele Levine, CEO Roy Morgan, says although mortgage stress is virtually unchanged in August, it has increased significantly since January and is set to go higher following this week's RBA interest rate increase:

“Mortgage stress is just one indicator of the pressure Australians are under – mortgage stress was virtually unchanged in August but is up significantly this year following three interest rate increases, while other factors include declining house prices in key markets, and a contracting Australian workforce compared to earlier this year are also pressuring Australians.
“The latest Roy Morgan data shows mortgage stress at 32.3% of mortgage holders (equivalent to 1,718,000) ‘At Risk’ in August, virtually unchanged from July, but up 8.4% points this year. Mortgage stress is just below an 18-year high since September 2008 (32.7%) amidst the Global Financial Crisis.
“During 2008, official Australian interest rates hit a 30-year high of 7.25% over a six-month period from March – September 2008 which led to record high levels of mortgage stress during this period, peaking at 35.6% in the three months to May 2008.
“The rise in mortgage stress this year has been driven by the Reserve Bank’s decision to raise interest rates three times by a total of +0.75% to 4.35% in May which has significantly increased mortgage repayments so far this year.
“In addition, Roy Morgan has modelled interest rate increases this week (+0.25% to 4.6%) and potentially in early November (+0.25% to 4.85%). With the rate rise this week, official interest rates will be at their highest for nearly 15 years since November 2011 and mortgage stress will be at an estimated 32.9% of mortgage holders in October 2026. This will increase to 33.9% of mortgage holders if there is another interest rate increase in November.
“Another factor contributing to rising mortgage stress in the last few months has been the changing composition of the workforce. Full-time employment has weakened considerably, and this has a direct, and negative, impact on household incomes. As household incomes come under pressure, this leads to an increase in mortgage stress. There was a slight increase in net household income in July / August which provided a small moderation to the level of mortgage stress.
“Until earlier this year the employment market had been strong for several years, but employment growth has stalled during 2026 and gone consistently backwards in the last few months. The latest Roy Morgan estimates show full-time employment at 9,012,000 in August 2026 – down 309,000 from 9,321,000 in January 2026 – before interest rates, and mortgage stress, began to rise again.”
These are the latest findings from Roy Morgan’s Single Source Survey, based on in-depth interviews conducted with over 60,000 Australians each year including over 10,000 owner-occupied mortgage-holders.
To learn more about Roy Morgan’s mortgage data, call (+61) (3) 9224 5309 or email askroymorgan@roymorgan.com. Please click on this link to the Roy Morgan Online Store.
About Roy Morgan
Roy Morgan is Australia’s largest independent Australian research company, with offices in each state, as well as in the U.S. and U.K. A full-service research organisation, Roy Morgan has over 80 years’ experience collecting objective, independent information on consumers.
[1] "At Risk" is based on those paying more than a certain proportion of their after-tax household income (25% to 45% depending on income and spending) into their home loan, based on the appropriate Standard Variable Rate reported by the RBA and the amount they initially borrowed.
[2] "Extremely at Risk" is also based on those paying more than a certain proportion of their after-tax household income (25% to 45% depending on income and spending) into their home loan, based on the Standard Variable Rate set by the RBA and the amount now outstanding on their home loan.
Margin of Error
The margin of error to be allowed for in any estimate depends mainly on the number of interviews on which it is based. Margin of error gives indications of the likely range within which estimates would be 95% likely to fall, expressed as the number of percentage points above or below the actual estimate. Allowance for design effects (such as stratification and weighting) should be made as appropriate.
| Sample Size | Percentage Estimate |
| 40% – 60% | 25% or 75% | 10% or 90% | 5% or 95% | |
| 1,000 | ±3.0 | ±2.7 | ±1.9 | ±1.3 |
| 5,000 | ±1.4 | ±1.2 | ±0.8 | ±0.6 |
| 7,500 | ±1.1 | ±1.0 | ±0.7 | ±0.5 |
| 10,000 | ±1.0 | ±0.9 | ±0.6 | ±0.4 |
| 20,000 | ±0.7 | ±0.6 | ±0.4 | ±0.3 |
| 50,000 | ±0.4 | ±0.4 | ±0.3 | ±0.2 |


